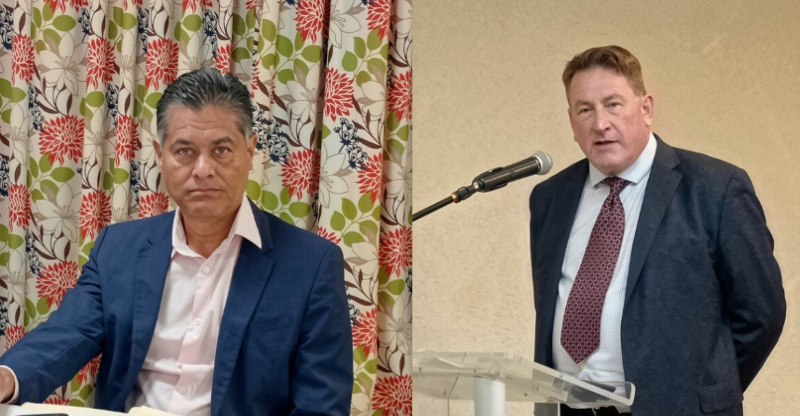

Doubling Barbados’ special loans ceiling to $5bn does not mean the country has taken on another $2.5bn in debt, Finance Minister Ryan Straughn has sought to clarify.
In a statement following Parliament’s approval of the Special Loans (Amendment) Bill, 2026, the minister said the higher limit was needed to replace approximately $1.2 billion in existing debt with cheaper financing, potentially saving $320m over time for healthcare.
He said: “We are working to replace about $1.2bn of existing debt with financing on better terms. We expect this could save the country approximately $320m over time, once the arrangements are finalised.”
The previous $2.5bn ceiling did not leave enough room for the replacement loans, which must be taken out under the Special Loans Act, he said.
The higher limit would accommodate the proposed refinancing and allow the government to pursue similar savings in future without amending the law each time, he added.
Straughn compared the arrangement to a family refinancing its mortgage: “Think about a family paying a mortgage. If that family can get a lower interest rate, they may be able to reduce what they pay every month. They still have a mortgage, but it costs them less. That is what we are doing for Barbados.”
The projected $320m represented savings accumulated through lower interest and other financing costs, rather than a new loan or an immediate cash payment, he stressed.
Those savings would support mental health services, community healthcare and the prevention and treatment of chronic illnesses, he added.
“This is about paying less on the debt we already have, so that more of our money goes to the care Barbadians need. That means more support for people living with diabetes and high blood pressure, stronger mental health services, and care closer to home.”
In an earlier interview with Barbados TODAY, economist Jeremy Stephen described the swap as a form of debt consolidation, in which backing from trusted institutions helps the Government attract lenders offering more favourable rates. He cautioned, however, that repayment obligations remained, alongside risks involving the management of funds and weak economic growth.
“All the same risks that would apply if they borrowed the money locally for capital projects still apply,” he said.
On accountability, the finance minister noted that loans were subject to parliamentary approval, publication and auditing by the Auditor General. It also promised to report directly to the public on what each loan delivers, including the health savings.
The replacement loans would be repaid from government revenue over many years, on terms approved by Parliament, Straughn said in the statement, noting that the amendment introduced no new taxes.
Full details of the financing arrangement are to be released once it is concluded, the finance minister said.
(BT)
The post Straughn: $5bn borrowing ceiling doesn’t mean extra debt appeared first on Barbados Today.